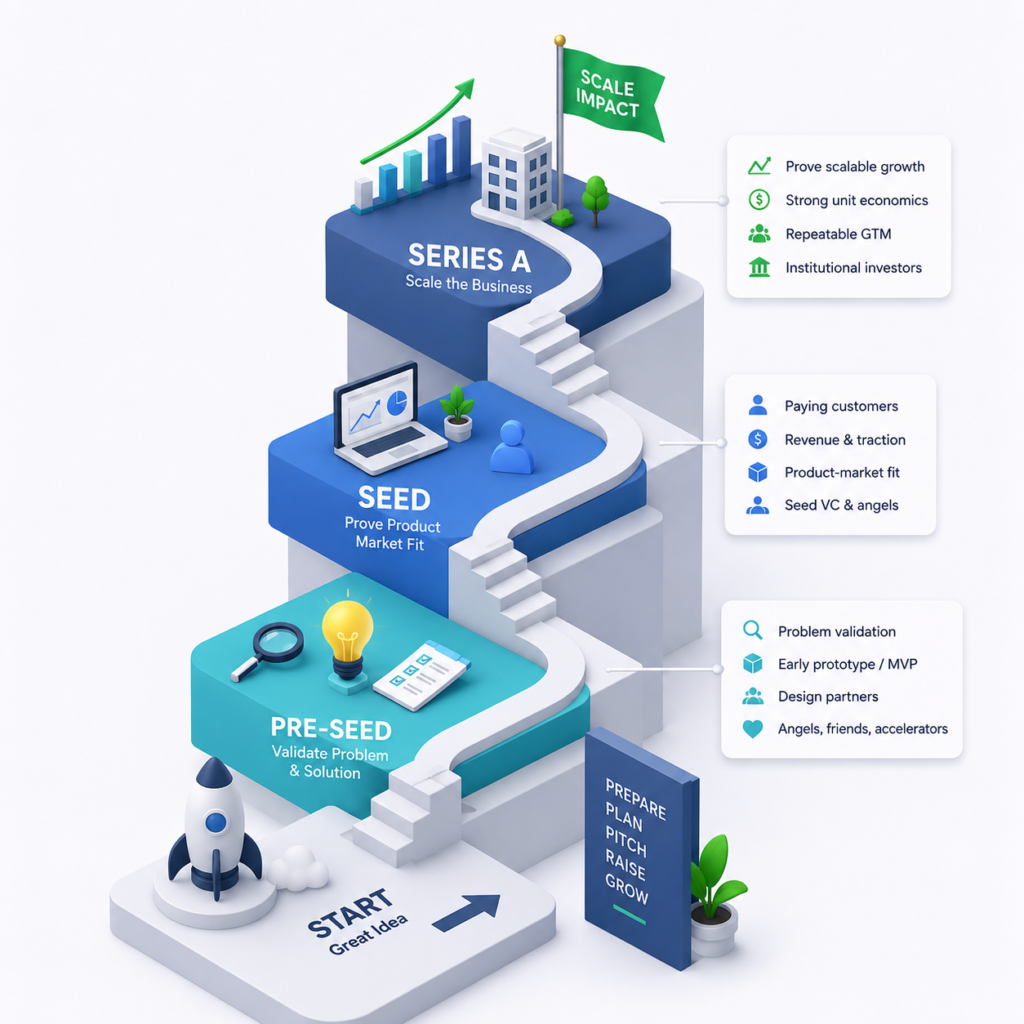
Startup fundraising is not one event. It is a process that begins with proving an idea, develops into proving customer demand, and eventually requires evidence that the business can scale.
The venture market is active in 2026, but capital remains highly concentrated. KPMG reported $227.4 billion invested across 8,440 global venture deals in Q2 2026, while Carta found that more than 60% of the funding recorded on its platform in Q1 went to AI companies. Investors are deploying capital, but not evenly across stages, sectors, or companies.
For founders, the message is straightforward:
A strong market does not make every startup fundable. You still need the right evidence, materials, investors, and fundraising process.
This guide explains what founders should prepare from pre-seed through Series A.
Fundraising Timeline: Table of Contents
| Section | What You Will Learn |
|---|---|
| 1 | How the 2026 fundraising market has changed |
| 2 | How to identify your real fundraising stage |
| 3 | What investors expect at pre-seed |
| 4 | What investors expect at seed |
| 5 | What investors expect at Series A |
| 6 | How much capital to raise |
| 7 | Which fundraising materials you need |
| 8 | How to find the right investors |
| 9 | How to run investor outreach |
| 10 | How meetings, diligence, and term sheets work |
| 11 | A practical fundraising timeline |
| 12 | Common mistakes to avoid |
1. Understand the 2026 Venture Market
The market appears stronger than it did during the recent funding slowdown, but the recovery is uneven. NVCA and PitchBook reported record investment and exit activity during the first half of 2026 while also warning that the broader recovery remained concentrated rather than evenly distributed across the venture ecosystem.
Carta reported rising valuations and lower dilution across many stages, but it also found that capital was increasingly concentrated in fewer, larger rounds. In 2025, total round count fell to a six-year low even as median valuations increased.
This creates a market with two realities:
- Strong companies in attractive sectors may receive high valuations and competitive investor interest.
- Startups without clear traction, differentiation, or investor fit may struggle to secure meetings.
Do not base your fundraising strategy on a highly visible AI mega-round or another exceptional transaction. Your company will be evaluated according to its own stage, geography, sector, traction, team, and investor demand.
2. Identify Your Real Fundraising Stage
Founders sometimes choose a round name based on the amount they hope to raise.
Investors usually look at the company’s progress.
| Stage | Main Question |
|---|---|
| Pre-seed | Is this an important problem, and can this team build a solution? |
| Seed | Is there evidence that customers want the product? |
| Series A | Is there evidence that the business can grow repeatedly and efficiently? |
The boundaries between stages are not universal. A capital-intensive biotechnology company and a software startup may raise very different amounts while still being considered the same stage.
Your stage should therefore be based on what has been proven, not only the round size.
3. Pre-Seed: Prove the Problem and the Team
At pre-seed, the company may have a concept, prototype, early product, or small group of users. Investors are often evaluating the founders, the problem, the market, and the quality of early validation.
Carta’s 2026 pre-seed research found that founders at this stage commonly raise from angels, accelerators, pre-seed funds, friends and family, and other early-stage investors. SAFEs remain the dominant early-stage financing instrument in Carta’s dataset.
What investors want to see
| Area | Useful Evidence |
|---|---|
| Problem | Customer interviews and proof that the pain is important |
| Product | Prototype, minimum viable product, or technical progress |
| Customers | Design partners, pilots, early users, or letters of intent |
| Market | A focused initial segment with expansion potential |
| Team | Relevant experience and the ability to build quickly |
| Plan | Clear milestones for the next 12–18 months |
Illustrative example
A stronger pre-seed story is:
We interviewed 70 procurement managers, built a working product, and secured five design partners that use it weekly.
A weaker version is:
We believe procurement is a large market and expect strong customer demand.
At pre-seed, investors do not expect the company to have removed every risk. They want evidence that the founders are learning quickly and reducing the most important uncertainties.
Common pre-seed financing structures
Pre-seed rounds are frequently raised through SAFEs or convertible notes rather than a full priced-equity financing. YC describes the SAFE as a simplified one-document security intended to reduce negotiation time and legal complexity, although founders still need to understand valuation caps, discounts, conversion, and dilution.
The correct instrument depends on your jurisdiction and circumstances. Obtain qualified legal advice before issuing securities.
4. Seed: Prove That Customers Want the Product
At seed stage, investors usually expect more than an idea and a prototype.
The company should be able to show that a real customer group is engaging with, using, or paying for the product. Seed funding is often used to develop product-market fit, strengthen the team, and build the first repeatable acquisition channels.
What investors may examine
| Area | Investor Focus |
|---|---|
| Traction | Revenue, users, contracts, pilots, or usage growth |
| Retention | Whether customers continue using or paying |
| Business model | Pricing and how revenue is generated |
| Go-to-market | How customers are found and converted |
| Economics | Gross margin, acquisition costs, and burn |
| Team | Whether the company can execute the next stage |
| Fundraising ask | How the round creates measurable progress |
Illustrative example
Consider two startups with the same monthly revenue.
Startup A
We generate $40,000 in monthly revenue.
Startup B
Monthly recurring revenue grew from $13,000 to $40,000 in ten months, 72% of pilots converted to annual contracts, and monthly churn declined to 3%.
Startup B provides more context. The investor can see growth, conversion, and retention rather than one isolated number.
What seed capital should achieve
A seed round should move the company toward a stronger commercial position, such as:
- A repeatable customer-acquisition channel
- Stronger product retention
- Meaningful recurring revenue
- A completed commercial product
- A stronger leadership team
- Evidence that the initial market can support growth
The objective is not simply to keep operating. It is to remove enough risk to make the company ready for the next stage.
5. Series A: Prove That the Business Can Scale
Series A is usually more institutional and more demanding than earlier rounds. It is commonly structured as a priced preferred-equity financing and typically involves more detailed financial, legal, technical, and commercial diligence.
Investors are no longer asking only whether customers want the product.
They are asking:
Can the company turn early success into a large, repeatable business?
What Series A investors may expect
| Area | Evidence |
|---|---|
| Growth | Consistent revenue or usage expansion |
| Retention | Customers remain, renew, or expand |
| Go-to-market | A channel that can produce repeatable results |
| Unit economics | Credible acquisition costs, margins, and payback |
| Market | A clear path toward a venture-scale outcome |
| Leadership | A team capable of managing growth |
| Financial plan | A realistic connection between capital and scaling |
| Data quality | Reliable metrics and organised reporting |
Series A decks are often more data-driven than pre-seed or seed presentations because institutional investors need stronger evidence that growth is repeatable.
Illustrative example
A stronger Series A story might be:
We reached $4 million ARR, grew 105% during the past year, maintain 114% net revenue retention, and have built a sales process that produces a predictable number of new contracts per representative.
The strongest metric will vary by business model. A marketplace, hardware company, consumer brand, and SaaS startup will not be assessed in exactly the same way.
6. Decide How Much Capital to Raise
Do not choose the fundraising amount because another startup at your stage raised the same amount.
Begin with the milestones you need to reach.
These might include:
- Completing the product
- Converting pilots into paying customers
- Reaching a revenue target
- Building a commercial team
- Entering a new market
- Securing regulatory approval
- Proving retention
- Reaching the next financing stage
Then calculate the hiring, product, marketing, operational, and working-capital costs required to reach them.
Weak fundraising ask
We are raising $2 million for product, hiring, marketing, and operations.
Stronger fundraising ask
We are raising $2 million to complete the enterprise product, hire four commercial team members, and grow annual recurring revenue from $600,000 to $2.1 million over approximately 18 months.
The second version explains what should become true after the investment.
Your calculation should include a reasonable cash buffer. Do not build a plan that requires you to close the next round immediately before the company runs out of money.
7. Understand Valuation and Dilution
Valuation determines the price of the company for the financing, while dilution shows how much existing ownership decreases after new securities are issued.
For example, raising $2 million at an $8 million pre-money valuation produces a basic $10 million post-money valuation, giving the new investor 20% before considering SAFEs, convertible notes, warrants, or an option-pool increase.
The final ownership may be different once all instruments convert.
Review:
| Item | Why It Matters |
|---|---|
| Pre-money valuation | Company value before new capital |
| Post-money valuation | Value after the investment is added |
| Existing SAFEs and notes | May convert and dilute current shareholders |
| Option-pool increase | May create additional founder dilution |
| Investor ownership | Affects economics and future rounds |
| Future dilution | Determines whether ownership remains sustainable |
Carta’s 2026 fundraising benchmarks show rising valuations and declining dilution in recent rounds, but those figures represent specific datasets and should not be treated as automatic pricing for every startup.
Your objective is not always to secure the highest possible valuation. It is to complete a healthy round that properly funds the company without making the next financing unnecessarily difficult.
8. Prepare the Core Fundraising Materials
Your materials should communicate one consistent investment case.
| Material | Purpose |
|---|---|
| Pitch deck | Explains the opportunity and creates investor interest |
| Financial model | Shows how the company grows and uses capital |
| Executive summary | Provides a concise overview |
| Cap table | Explains current and future ownership |
| Data room | Supports claims with evidence |
| Use of funds | Connects capital to milestones |
| Investor list | Focuses outreach on suitable investors |
| Outreach message | Creates a reason to review the opportunity |
The pitch deck, model, cap table, and data room should agree on revenue, customers, fundraising amount, runway, hiring, and milestones.
9. Find Investors Who Fit Your Round
A large investor database is not automatically a good investor list.
Each target should have a credible reason to consider your company.
Research:
| Criterion | What to Confirm |
|---|---|
| Stage | Does the investor fund companies at your stage? |
| Sector | Does the investor understand your subsector? |
| Geography | Does it invest where your company operates? |
| Check size | Does its normal investment fit your round? |
| Recent activity | Is it currently deploying capital? |
| Portfolio | Are there relevant investments or conflicts? |
| Partner fit | Who is the right person inside the fund? |
| Lead preference | Does it lead, follow, or do both? |
For example, a European fintech startup raising a $1.5 million seed round should not prioritise a US growth investor whose normal first check is $15 million.
A smaller list of well-matched investors will usually support stronger personalisation and better conversations than a large unfiltered list.
10. Run Investor Outreach as a Structured Campaign
A good outreach email should quickly answer:
- Why are you contacting this investor?
- What does the company do?
- What evidence shows that it is working?
- How much are you raising?
- What should the investor do next?
Example
Hi Sarah,
I noticed your investments in vertical SaaS and logistics technology.
We help regional freight operators reduce empty journeys through automated route planning. We currently support 75 fleets, generate $46K MRR, and have grown revenue 3.1× during the past year.
We are raising a $1.6M seed round to build the commercial team and enter two additional markets.
Would you be open to reviewing our deck?
Contact investors in organised groups rather than emailing the entire list at once.
Track replies, meetings, feedback, follow-ups, partner discussions, diligence, and commitments through a fundraising CRM.
11. Prepare for Investor Meetings
The meeting is not simply a presentation.
Investors may interrupt, skip slides, or spend most of the conversation on one issue such as retention, competition, valuation, or customer acquisition.
Prepare to explain:
- The problem and why it matters
- The product
- Traction
- Market opportunity
- Business model
- Customer acquisition
- Competition
- Team
- Financial assumptions
- Burn and runway
- Fundraising amount
- Milestones
A useful test is to identify the three hardest questions each slide may create.
For example:
| Slide | Likely Question |
|---|---|
| Traction | Is this growth repeatable? |
| Market | How did you calculate the initial market? |
| Competition | Why will a larger company not copy this? |
| Financials | What happens if growth is slower? |
| Fundraising ask | Why do you need this exact amount? |
Do not memorise every sentence. Understand the message and evidence behind each slide.
12. Organise the Data Room Before Diligence
An investor data room should be ready before serious outreach begins, even though you will not share every document immediately.
A simple structure includes:
| Folder | Main Documents |
|---|---|
| 1. Company | Incorporation and governance |
| 2. Ownership | Cap table, SAFEs, notes, previous financing |
| 3. Financials | Historical results, model, cash flow, tax |
| 4. Customers | Revenue, contracts, retention, pipeline |
| 5. Product | Demo, overview, roadmap, technology |
| 6. Legal and IP | Material contracts, IP assignments, licences |
| 7. Team | Founder, employee, and contractor agreements |
| 8. Fundraising | Deck, use of funds, milestones, dilution |
Share information in stages.
| Fundraising Stage | Typical Access |
|---|---|
| Initial outreach | Pitch deck and short summary |
| After first meeting | Key metrics and financial summary |
| Serious interest | Full model, ownership summary, customer evidence |
| Due diligence | Corporate, legal, financial, customer, IP, and employment documents |
| After term sheet | Full restricted diligence room |
| Closing | Final agreements, approvals, and updated cap table |
13. Understand Due Diligence
Due diligence tests whether the claims made during fundraising are accurate.
Investors may review:
- Company formation
- Ownership
- Financial records
- Customer contracts
- Revenue quality
- Product and technology
- Intellectual property
- Employment agreements
- Legal risks
- Tax compliance
- Founder references
A problem does not always end the investment.
However, an undisclosed or unexplained issue can damage trust more than the issue itself.
14. Review the Entire Term Sheet
The highest valuation is not always the best offer.
Review the full combination of economics, control, and future flexibility.
| Term | Founder Question |
|---|---|
| Valuation | Is it pre-money or post-money? |
| Option pool | Who absorbs the dilution? |
| Liquidation preference | Who receives proceeds first? |
| Board seats | Who controls the board? |
| Protective provisions | Which decisions require investor consent? |
| Founder vesting | Is previous work recognised? |
| Pro rata rights | Who can maintain ownership later? |
| Anti-dilution | What happens in a down round? |
| Exclusivity | How long are you prevented from speaking with others? |
| Closing conditions | What can still stop the deal? |
NVCA publishes widely used model documents for institutional venture financings, but every transaction still requires advice from qualified legal and tax professionals familiar with the relevant jurisdiction.
15. Follow a Realistic Fundraising Timeline
Fundraising preparation should begin before the company urgently needs capital.
| Timing | Main Priority |
|---|---|
| 6–12 months before outreach | Strengthen traction and track relevant metrics |
| 3–6 months before outreach | Prepare the model, deck, cap table, and data room |
| 8–12 weeks before outreach | Build and verify the investor list |
| 4–8 weeks before outreach | Prepare messages and rehearse meetings |
| Launch | Contact investors in focused groups |
| During meetings | Track feedback, follow-ups, and momentum |
| Serious interest | Begin controlled diligence |
| Term sheet | Negotiate the complete offer |
| Closing | Finalise documents, approvals, and funding |
The process may take longer at Series A because institutional rounds typically involve more extensive diligence and legal documentation than early SAFE or angel rounds.
16. Avoid the Most Common Fundraising Mistakes
The most damaging mistakes are often preparation mistakes.
| Mistake | Better Approach |
|---|---|
| Starting outreach too early | Complete the core materials first |
| Contacting every investor | Target investors based on fit |
| Using vague language | Explain the company simply |
| Showing metrics without context | Include time periods and definitions |
| Building unrealistic forecasts | Use operational assumptions |
| Choosing a random round size | Connect capital to milestones |
| Ignoring dilution | Model the fully diluted ownership |
| Waiting to organise diligence | Build the data room before outreach |
| Focusing only on valuation | Review all term-sheet provisions |
| Treating fundraising casually | Run it as a managed campaign |
The Pre-Seed-to-Series-A Checklist
| Area | Pre-Seed | Seed | Series A |
|---|---|---|---|
| Main objective | Validate the problem | Prove customer demand | Prove repeatable growth |
| Product | Prototype or early product | Usable commercial product | Scalable product |
| Traction | Interviews, pilots, design partners | Customers, revenue, retention | Growth, retention, efficiency |
| Team | Core founders | Core operating team | Scalable leadership |
| Financial model | Milestone-based | Driver-based forecast | Detailed scaling plan |
| Investor type | Angels, accelerators, pre-seed funds | Angels, seed and micro-VC funds | Institutional venture funds |
| Common structure | SAFE, note, or small equity round | SAFE, note, or priced seed | Priced preferred-equity round |
| Diligence | Focused | More detailed | Extensive |
| Round outcome | Build and validate | Prove the model | Scale the model |
Fundraising in 2026 Rewards Prepared Founders
The venture market is active, but investors remain selective.
A startup does not become fundable simply because it operates in a growing sector or because comparable companies have received high valuations.
Founders need to show:
A clear problem, meaningful evidence, credible numbers, a capable team, a large opportunity, and a specific plan for using investment capital.
At GetPitchRaise, we support early-stage founders through three stages:
1. Pitch Deck and Financial Model Assessment
We review your current materials to identify unclear messaging, inconsistent figures, unsupported assumptions, and likely investor questions.
2. Fundraising Material Development
We help develop investor-ready materials that present one clear and consistent fundraising story.
3. Investor Outreach
We research suitable investors and support structured outreach based on your stage, sector, geography, check size, and fundraising objectives.
Preparing to Raise from Pre-Seed to Series A?
Book a free consultation call now to review your fundraising materials and prepare for investor outreach.